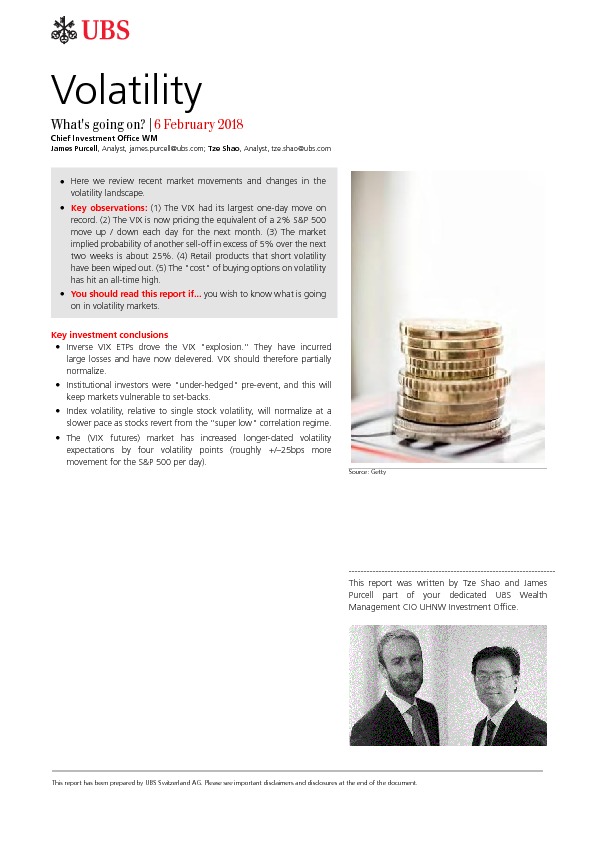
Inverse VIX ETPs drove the VIX "explosion." They have incurred large losses and have now delevered. VIX should therefore partially normalize. Institutional investors were "under-hedged" pre-event, and this will keep markets vulnerable to set-backs.
Index volatility, relative to single stock volatility, will normalize at a slower pace as stocks revert from the "super low" correlation regime. The (VIX futures) market has increased longer-dated volatility expectations by four volatility points (roughly +/–25bps more movement for the S&P 500 per day).
Continuer la lecture de cet article ?
Inscrivez-vous gratuitement et obtenez un accès à
Investment Officer France:
Investment Officer France:
- Exclusif pour les investisseurs professionnels
- Annulez à tout moment
- Accès illimité : web, application et newsletters
L'inscription prend moins d'une minute.
Aucune information de paiement requise
Inscrivez-vous gratuitement et obtenez un accès à
Investment Officer Belgique:
Investment Officer Belgique:
- Exclusif pour les investisseurs professionnels
- Annulez à tout moment
- Accès illimité : web, application et newsletters
L'inscription prend moins d'une minute.
Aucune information de paiement requise
Inscrivez-vous gratuitement et obtenez un accès à
Investment Officer Luxembourg:
Investment Officer Luxembourg:
- Exclusif pour les investisseurs professionnels
- Annulez à tout moment
- Accès illimité : web, application et newsletters
L'inscription prend moins d'une minute.
Aucune information de paiement requise